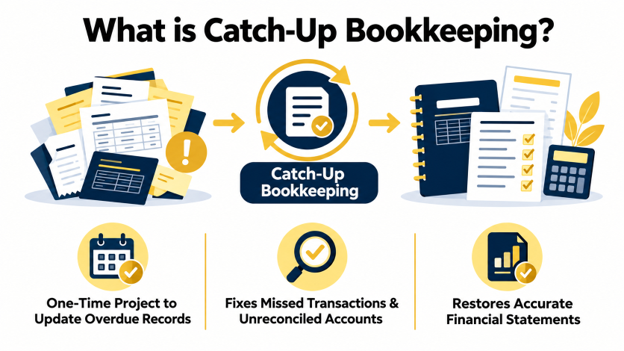
Catch-up bookkeeping is a one-time process of bringing unrecorded transactions, missed reconciliations, and unreliable financial statements up to date. This is different from ongoing bookkeeping, which maintains records monthly in real time.
This article explains catch-up bookkeeping in detail, including its process, costs, and how to decide if your business needs it now.
Also, if you’re behind on books, dealing with inconsistent tracking, or facing missed transaction entries, you can work with professional bookkeeping services to bring your records back on track.
What is Catch-Up Bookkeeping?
Catch-up bookkeeping is the process of updating overdue, incomplete, or unreconciled financial records after they have been neglected or left unorganized for a period of time.
Unlike ongoing bookkeeping, which records and reconciles transactions on a regular schedule, catch-up bookkeeping focuses on past records that need attention. The goal is to update the general ledger, reconcile accounts, prepare accurate financial statements, and return to a regular bookkeeping schedule.
That said, books can fall behind for many reasons, including limited time, staff changes, software transitions, or manual bookkeeping.
In fact, according to SMB Group, 11% of small businesses primarily rely on spreadsheets for accounting and financial management, and 8% use no software at all. As transaction volume grows, these manual methods can make it harder to keep financial records accurate and current.
When Does a Business Need Catch-Up Bookkeeping?
A business needs catch-up bookkeeping services when its financial records are too far behind to provide an accurate picture of its finances. A professional bookkeeper can help identify missing transactions, reconcile accounts, and bring your records up to date.
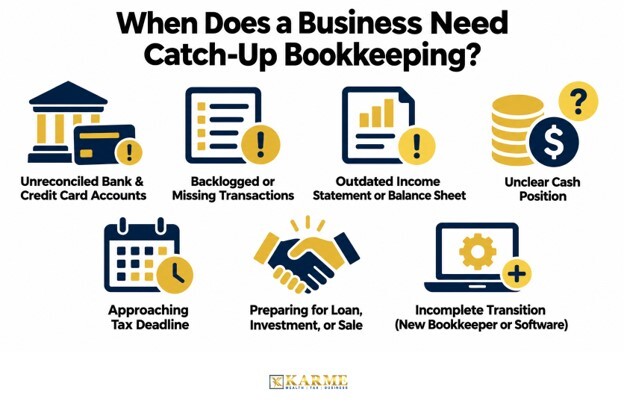
Common signs that your business needs catch-up bookkeeping services include:
- Unreconciled accounts: Bank and credit card accounts have gone months without reconciliation.
- Backlogged financial records: Transactions are missing, unentered, or uncategorized.
- Outdated financial statements: Your income statement or balance sheet is too old to guide decisions.
- Unclear cash position: You do not know your current cash balance, expenses, or profit.
- An approaching tax deadline: Your books are not ready for accurate tax filing.
- Loan, investment, or sale preparation: You need accurate financial records for due diligence or financing.
- An unfinished transition: A change in bookkeepers, accountants, or software left your QuickBooks records incomplete.
What Does Catch-Up Bookkeeping Involve?
catch-up Bookkeeping involves bringing overdue financial records up to date. A bookkeeper reviews past records, enters missing transactions, fixes errors, and reconciles accounts until the books are current.
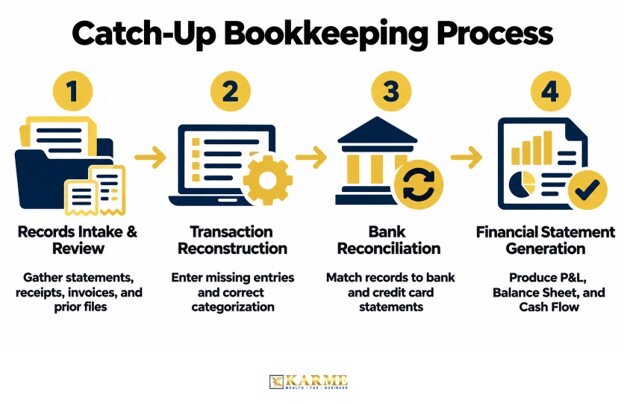
The process involves four main stages:
1. Records Intake and Review
The bookkeeper gathers bank and credit card statements, receipts, invoices, prior tax returns, and accounting files. These records show which months are incomplete and what is missing.
2. Transaction Reconstruction
The bookkeeper enters missing transactions and corrects incorrectly categorized entries. They compare transactions with source documents to ensure the general ledger accurately reflects income and expenses.
3. Bank Reconciliation
The bookkeeper compares accounting records with bank and credit card statements. They investigate differences, correct errors, and reconcile each month until the books are current.
4. Financial Statement Generation
Once the books are updated, the bookkeeper prepares financial statements, including the profit and loss statement, balance sheet, and cash flow statement. These reports show the business’s current financial position.
How Much Does Catch-Up Bookkeeping Cost?
The catch-up bookkeeping price depends on how far behind your books are and how much cleanup they need. Costs can vary based on:
- Months or years behind
- Number of bank and credit accounts
- Transaction volume
- Condition of your records
- Errors or duplicate entries
- Payroll or complex transactions
- Available accounting software and records
Catch Bookkeeping Pricing Models
Bookkeepers usually use one of these pricing models:
- Hourly rate: Pay for the time spent on the work.
- Flat project fee: Pay a set price for the agreed catch-up work.
- Monthly package: Pay a fixed amount based on the months being caught up.
In short, the more complex the cleanup, the more catch-up bookkeeping may cost.
Does Your Business Need Catch-Up Bookkeeping?
You may need catch-up bookkeeping if your financial records are several months behind, unreconciled, or difficult to verify. If your books are current and your accounts are reconciled, you can usually continue with regular bookkeeping.
Ask yourself these questions to decide if you need catch-up bookkeeping:
- Can I produce a reliable, recent financial statement right now?
- Have my accounts gone unreconciled for several months?
- Am I unsure whether past transactions were recorded correctly?
- Is a tax or financing deadline approaching with incomplete records?
If you answered yes to any of these questions, catch-up bookkeeping may be the right next step. Once your records are current and accurate, a monthly bookkeeping checklist can help keep them on track on a regular basis.
Why Acting Early Matters
Delaying your bookkeeping can also create problems when you need accurate financial records to prepare tax returns, apply for financing, or make business decisions. For example, the IRS failure-to-file penalty is 5% of unpaid tax for each month or part of a month that a return is late, up to 25%. Getting your books current sooner can help you file your back taxes on time before they accumulate additional penalties.
FAQs
Q1. Can I do catch-up bookkeeping myself, or do I need a professional?
If the gap is short and your records are simple, you can handle catch-up bookkeeping yourself. But if you are several months behind or dealing with multiple accounts, a professional can help prevent reconciliation errors and missed deductions.
Q2. How long does catch-up bookkeeping typically take to complete?
It depends on how far behind you are and how organized your records are. A simple catch-up may take a few days. A multi-year cleanup can take several weeks.
Q3. Will catch-up bookkeeping trigger an IRS audit?
No. Catching up your records does not trigger an IRS audit. In fact, accurate, complete records can help reduce the risk of errors compared with leaving gaps or filing incomplete returns.
Q4. Can catch-up bookkeeping be done while I keep running my business normally?
Yes. You do not have to put your business on hold. A bookkeeper can work in the background using the statements and records you provide while you continue your daily operations.
Q5. What records do I need to provide to start catch-up bookkeeping?
Start with your bank and credit card statements, invoices, receipts, and payroll records if applicable. You may also need to provide access to your accounting software or existing bookkeeping files.
Q6. Does catch-up bookkeeping include preparing my back tax filings too?
Not usually. Catch-up bookkeeping gets your financial records accurate and up to date so they are ready for tax filing. Preparing and filing the actual tax returns is a separate but related step.
Final Words
Catch-up bookkeeping brings overdue and unreconciled records up to date, so you can trust your numbers again. Staying current helps you avoid penalties, make better decisions, and keep your financial records in good shape.
At Karme, we handle catch-up, reconciliation, and monthly bookkeeping for businesses that have fallen behind. Whether you have missing transaction entries or inconsistent expense tracking, our team can organize your records and bring your books back on track. Get in touch today to keep your records ready for tax filing, loan applications, and financial reporting.